
You enter £50 in an online casino cashier, type your credit-card details, and click deposit. A second later, you either see £50 in your casino balance or an annoying “payment declined” message.
What happened during that second is more complicated than it appears.
Learning How Credit Card Casino Payments Work helps explain why casinos can accept one card and reject another, why banks recognise gambling purchases, and why some countries block credit-card deposits completely.
It also helps you understand fees and withdrawals before borrowed money reaches a gambling account.
A Casino Deposit Travels Through Several Companies
The casino is only one participant in a card transaction.
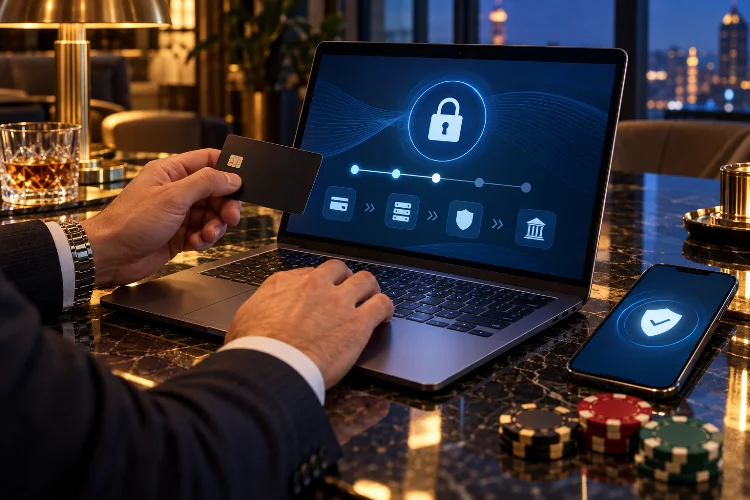
When you submit a deposit, the merchant sends the payment request to its payment processor or acquiring institution. The request then travels through the relevant card network toward your issuing bank.
Visa describes a standard digital payment lifecycle that moves from authentication to authorization, clearing, and settlement.
The issuing bank makes the key authorization decision.
It can examine available credit, card status, fraud signals, transaction information, and other risk criteria before approving or declining the request.
Once an approval returns through the network, the casino can normally make funds availble in your player account.
Final settlement between financial institutions takes place later.
Why Your Bank Knows It Is a Gambling Payment
The name appearing on your statement is not the only clue.
Card networks use merchant category codes to classify businesses and transactions.
Mastercard’s current merchant guidance identifies MCC 7995 specifically as Gambling Transactions, including wagers and casino gaming activity. Mastercard also requires non-face-to-face gambling merchants to follow particular registration requirements.
Visa likewise uses MCC 7995 for relevant online gambling transactions and requires online gambling merchants to have appropriate authority to operate.
This coding means your issuer can identify gambling spending separately from ordinary categories such as groceries, restaurants, or electronics.
A bank can therefore block casino payments without blocking the card itself.
The transaction code can also affect fees, rewards eligibility, and other issuer-specific treatment.
Why a Casino Deposit May Require an Extra Security Check
Card-not-present transactions have additional fraud risks because neither the physical card nor the customer is standing in front of the merchant.
That is where technologies such as EMV 3-D Secure come in.
Visa Secure, for example, uses 3-D Secure to allow information to pass between merchants and issuers so the issuer can authenticate customers and evaluate transaction risk.
You might be asked to approve the transaction in your banking app, enter a security code, or complete another challenge.
Sometimes the process happens in the background with no visible interruption.
Authentication still does not guarantee approval.
After confirming that you appear to be the cardholder, the issuer must separately determine whether the payment itself is permitted.
That distinction explains why you can pass the security check and still receive a decline.
Why Banks Decline Gambling Transactions
There is no single reason for a rejected casino deposit.
Your card may not have enough available credit. The transaction could trigger fraud monitoring, the card may be restricted from international purchases, or the issuer may simply prohibit gambling activity.
Regulation is another major factor.
In Great Britain, UK Gambling Commission rules prohibit covered gambling businesses from accepting credit-card payments for online casino gambling, betting, bingo, and certain other gambling services. The prohibition came into effect on April 14, 2020.
The restriction even covers attempts to route credit-card money into gambling through certain money-service businesses.
That matters because an e-wallet does not automatically convert prohibited borrowed funds into an acceptable casino deposit.
In jurisdictions where credit-card gambling remains legal, issuer policies can still differ.
Gambling Payments Can Cost More Than Normal Purchases
A £100 casino deposit does not always cost exactly £100.
Where credit-card gambling is permitted, some issuers may treat gambling as a cash advance or cash-equivalent transaction rather than an ordinary retail purchase.
Cash advances commonly operate under different pricing terms.
Depending on your agreement, this could mean an additional charge and a different interest calculation. Some historical American Express agreements, for example, have explicitly included gambling transactions within their cash-advance definitions.
Foreign currency can add another layer.
If your card is denominated in euros while the casino processes deposits in another currency, the issuer or payment chain may apply currency conversion and potentially a foreign-transaction fee.
Always check the current fee schedule for your actual card because these rules vary substantially between issuers.
Why Credit Card Gambling Became a Regulatory Issue
Credit cards differ from debit cards in one fundamental way: the money is borrowed.
That creates a particular concern when combined with gambling losses.
When the UK Gambling Commission announced its credit-card ban in 2020, it cited research indicating that 22% of surveyed online gamblers who used credit cards to gamble were classified as problem gamblers, with additional users considered at some risk of harm.
The regulator described the ban as a way of reducing the risk of consumers gambling with money they did not have.
Its later monitoring found that consumer support for the restriction was largely positive and reported no evidence at that stage of major harmful displacement toward other high-cost credit sources.
Other markets take different regulatory approaches, which is why payment availability should never be assumed from the card logo alone.
Can Casino Winnings Be Paid Back to a Credit Card?
Potentially, where local law, casino policy, the network, and the issuing bank allow it.
Card payouts are not identical to deposits.
Visa uses a mechanism called an Original Credit Transaction for certain payments sent to card accounts. Its rules state that eligible gambling winnings can be disbursed using OCTs and set conditions around the original payment credential and lawful gambling transaction.
Mastercard gateway documentation similarly includes a dedicated GAMING_WINNINGS disbursement type for gambling merchants operating under MCC 7995.
However, a casino may still offer a different withdrawal method.
For example, an operator might accept a particular card for deposits but require bank transfer or another supported channel for withdrawals.
Payment availability is therefore best checked in both the deposit and withdrawal sections of the cashier.
Why Withdrawals Usually Take Longer Than Deposits
Card authorization can happen in seconds. Withdrawals often involve more steps before the payment is even sent.
A regulated casino may need to complete customer identity checks, payment-method verification, fraud analysis, anti-money-laundering controls, or account reviews.
The operator might also have an internal pending period before releasing the payout.
Once the casino actually submits an eligible card disbursement, the financial networks and issuing institution still need to process it.
That is why “instant credit-card deposit” and “instant credit-card withdrawal” should not be treated as equivalent promises.
Never cancel a legitimate withdrawal simply because another payment method advertises quicker gambling access.
Credit Cards, Debit Cards, and E-Wallets Are Not the Same
The card might look nearly identical, but the source of money matters.
A debit-card purchase normally draws from funds in a bank account. A credit card creates borrowing against an approved credit line.
An e-wallet adds another layer between the player and casino, but the underlying funding source can still matter to regulators.
The UK Gambling Commission specifically requires operators to prevent prohibited credit-card funding from being channelled through e-wallets and other money-service businesses.
This is why payment rules can feel more complicated than simply asking, “Does this casino accept this wallet?”
Compliance systems may need to understand where the money originated.
What to Check Before Making a Deposit
Start with legality and availability.
Confirm that the casino is licensed for your market and that credit-card gambling is permitted there. Then check whether your particular card network and issuer allow gambling transactions.
Read the card agreement for cash-advance fees, interest, currency conversion, and other charges.
Next, review casino limits and withdrawal rules.
Most importantly, remember that a credit limit is not a gambling budget.
Borrowing £500 from a card does not mean £500 is affordable to lose. Interest can continue adding to the cost long after the casino session ends.
If you cannot comfortably repay a deposit from existing income or savings, using credit to fund gambling can turn a short entertainment expense into a much longer financial obligation.
Understanding How Credit Card Casino Payments Work explains why a deposit may involve authentication, merchant coding, issuer approval, and several financial intermediaries before reaching your account.
Rules also vary sharply by jurisdiction, and fees can make borrowed gambling funds more expensive.
Before depositing, confirm that the payment is permitted, understand your card’s terms, and use only money you can afford to lose rather than treating available credit as spendable cash.
